The list price tells you what a home costs to buy. It does not tell you what it costs to own. Before you make an offer, it pays to understand the full picture, both what you will need at closing and what you will spend every month after.
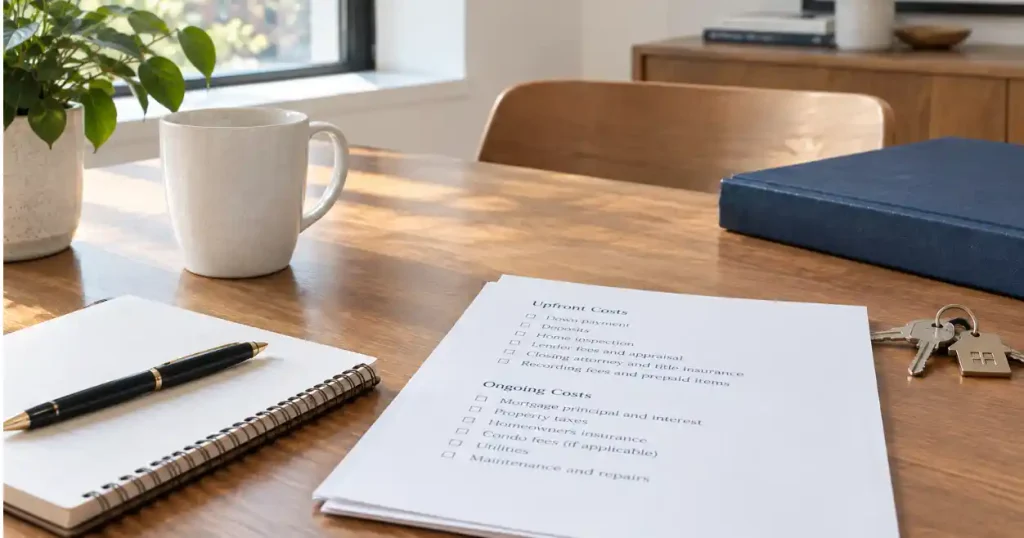
Upfront Costs
- Down payment: Commonly 3 to 20 percent of the purchase price, depending on your loan program.
- Deposits: In Massachusetts, buyers typically put down an initial deposit with the offer and a larger deposit when signing the Purchase and Sale Agreement. These are credited toward your down payment.
- Home inspection: Plus any specialized inspections, such as radon, pests, sewer line, or lead paint for older homes.
- Lender fees and appraisal: Origination charges, the appraisal, and credit report fees.
- Closing attorney and title insurance: Massachusetts closings are handled by attorneys, and lender’s title insurance is generally required. Owner’s title insurance is optional but strongly recommended.
- Recording fees and prepaid items: Recording the deed and mortgage, plus prepaid property taxes, homeowners insurance, and interest.
Ongoing Costs
- Mortgage principal and interest
- Property taxes: Rates vary by city. Somerville and several neighboring communities offer a residential exemption for owner-occupants, which can noticeably lower your bill. Confirm eligibility and filing deadlines with the city.
- Homeowners insurance: Plus flood insurance if the property is in a flood zone.
- Condo fees: Review what they cover, the health of the reserve fund, and any upcoming special assessments.
- Utilities: Older Greater Boston housing stock can carry high heating costs. Ask for 12 months of utility history.
- Maintenance and repairs: A common rule of thumb is to set aside 1 to 2 percent of the home’s value each year.
Costs Buyers Often Overlook
Moving expenses, immediate repairs found at inspection, furnishing a larger space, and parking permits can all add up. For multifamily buyers, factor in vacancy, tenant turnover, and capital reserves when you evaluate the numbers.
How We Help
We build a full cost picture for every property you seriously consider, so you can compare homes on what they truly cost, not just their list price. We also connect you with trusted lenders, attorneys, and inspectors to keep the process organized.
This article is for general information. Speak with your lender and attorney about the specifics of your purchase.
Reach out at any time to discuss your goals.
Our team manages every step, from your first tour through closing.
Contact us to walk through any of the three residences.
Stephen, Ciampa Group
(617) 221-6307 | stephen@ciampagroup.com | ciampagroup.com